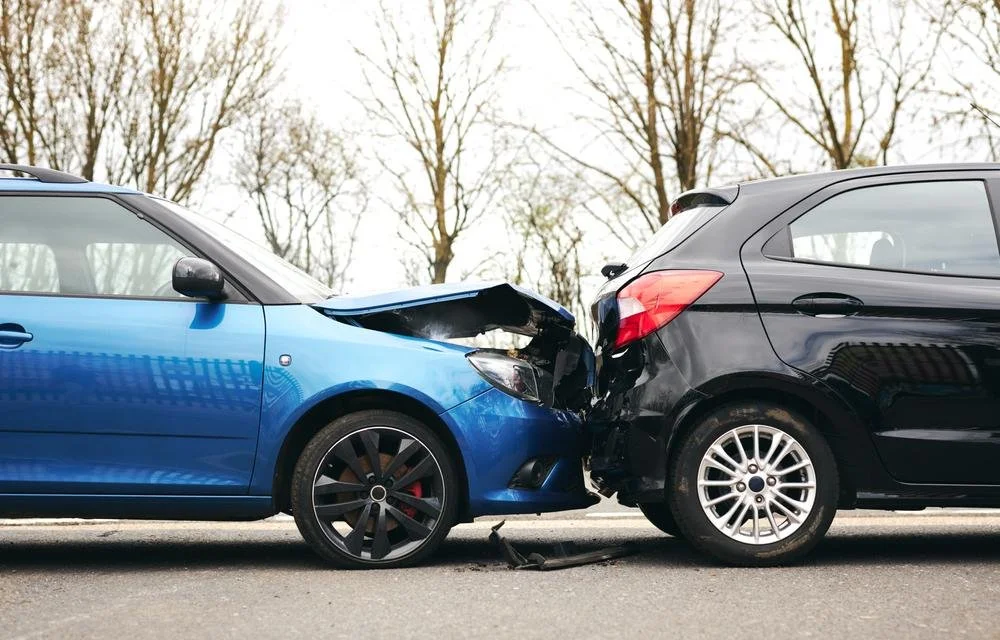
Imagine you're driving to work, running errands, or heading home when another driver hits your vehicle. After exchanging information, you discover something frustrating: the other driver doesn't have auto insurance.
Unfortunately, this situation can leave you wondering who will pay for your vehicle repairs, medical expenses, and other damages.
Being involved in an accident with an uninsured driver can be stressful, but having the right auto insurance coverage can make a big difference.
At William Penn Insurance, we believe understanding your coverage before an accident happens is one of the best ways to protect yourself financially.
1. Who Pays for the Damage If the Other Driver Has No Insurance?
When an at-fault driver doesn't have insurance, recovering compensation directly from that driver may be difficult.
However, your own auto insurance policy may help cover certain expenses depending on the coverage you selected.
Two important coverages to understand are:
Collision Coverage: Helps pay to repair or replace your vehicle after an accident involving another vehicle or object, regardless of who caused it, subject to your policy terms and deductible.
Uninsured Motorist Coverage (UM): Helps protect you and eligible household members and passengers against injuries caused by an at-fault driver who has no insurance. In Pennsylvania, this coverage generally does not pay for damage to your vehicle.
Understanding the difference between these coverages is important when choosing an auto insurance policy.
2. What Is Uninsured Motorist Coverage?
Uninsured Motorist Coverage, commonly called UM coverage, is designed to protect you if you're injured in an accident caused by a driver who doesn't have auto insurance.
For example, imagine another driver runs a red light and hits your vehicle. You suffer injuries, but the driver has no insurance to cover your damages.
If you have UM coverage, your policy may help pay for eligible injury-related damages, subject to your coverage limits and policy conditions.
In Pennsylvania, insurance companies are required to offer uninsured motorist coverage, but drivers can choose to reject it in writing.
That's why it's important to review your policy and understand what protection you currently have.
3. What If the Other Driver Has Insurance, But Not Enough?
This is where Underinsured Motorist Coverage (UIM) becomes important.
UIM coverage is designed to help when the at-fault driver has insurance, but their policy limits aren't enough to cover your eligible injury-related damages.
For example:
Imagine you're injured in an accident, and the other driver's insurance coverage isn't enough to cover your damages. If you have UIM coverage, your policy may help cover the remaining eligible amount, subject to its limits and conditions.
Remember: UM and UIM coverage generally protect against bodily injury, not damage to your vehicle.
4. What Should You Do After an Accident With an Uninsured Driver?
If someone hits your car and doesn't have insurance, follow these steps:
1. Make sure everyone is safe.
Check for injuries and move to a safe location if possible. Call 911 if anyone is injured or there's an emergency.
2. Contact the police.
Report the accident and request assistance documenting what happened.
3. Collect information.
Get the other driver's name, phone number, license plate number, and vehicle information. Take pictures of the vehicles, damage, and accident scene.
4. Contact your insurance company.
Report the accident as soon as possible. Your insurance company can explain which coverages may apply and guide you through the claims process.
5. Review your coverage.
Check whether your policy includes collision, uninsured motorist, and medical benefits coverage.
Taking these steps can help make the claims process easier and ensure you understand your options.
5. How Can You Protect Yourself From Uninsured Drivers?
You cannot control whether every driver on the road has insurance, but you can make informed decisions about your own coverage.
Here are a few things to consider when reviewing your auto insurance policy:
Consider collision coverage to help protect your vehicle after an accident.
Ask about Uninsured Motorist Coverage to protect against eligible injuries caused by uninsured drivers.
Consider Underinsured Motorist Coverage in case another driver's insurance isn't enough.
Review your medical benefits and available limits.
Compare insurance options to find coverage that fits your needs and budget.
Having the right coverage can help you avoid unexpected financial stress when an accident happens.
Final Thoughts: Don't Wait Until an Accident Happens to Review Your Insurance
An accident involving an uninsured driver can happen when you least expect it. While you cannot control other drivers, you can take steps to make sure your insurance policy offers the protection you need.
At William Penn Insurance, we help Pennsylvania drivers compare insurance options from multiple carriers and understand their coverage choices.
Whether you're looking for affordable auto insurance, better protection, or simply want to review your current policy, our team is here to help.
Don't leave your protection to chance. Compare your options and get a free auto insurance quote today!
Contact William Penn Insurance
📍 1120 Roosevelt Ave, Suite A, York, PA 17404
📞 Call: (717) 900-8658
📱 Text: (717) 309-1636
🌐 Website: https://www.williampenninsurance.com/
William Penn Insurance – You deserve better. Get smarter insurance.
Insurance coverage, exclusions, limits, and deductibles vary by policy and carrier. This article is for general educational purposes and is not a substitute for reviewing your individual policy.